-
Shop
- Advanced Technologies
- Best-Sellers
- Car Accessories
- Dating & Social Skills
- Digital Resources
- Budgeting & Saving
- Emotional Intelligence
- Entrepreneurship & Business Growth
- Financial Independence
- Financial Mindset & Psychology
- Goal Setting
- Leadership
- Mindfulness
- Motivation
- Online Business
- Positive Thinking
- Productivity
- Self Confidence
- Sleep Improvement
- Stress Management & Relaxation
- Yoga & Mind-Body Practices
- Education & Learning
- Family & Parenting
- Fashion
- Alexander McQueen
- Bags
- Bags & Wallets
- Balenciaga
- Belts
- Blazers
- Blouses & Shirts
- Bottega Veneta
- Bottoms
- Brunello Cucinelli
- Burberry
- Chanel
- Chloé
- Dior
- Dolce & Gabbana
- Dresses
- Etro
- Fendi
- Gucci
- Jacquemus
- Jewelry
- Jil Sander
- Keychains
- Kiton
- Luggage
- Luggage Bags
- Miu Miu
- Off-White
- Outerwear
- Prada
- Rick Owens
- Saint Laurent
- Shoes
- Socks & Tights
- The Row
- Tom Ford
- Valentino
- Valentino Garavani
- Versace
- Vivienne Westwood
- Fashion Accessories
- Furniture
- Gadgets
- Guess
- Headphones
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Supplies
- Kids & Babies
- Kitchen
- Kitchen Best-Sellers
- Lighting
- Patio, Lawn & Garden
- Personal Growth
- Pet Care
- Pet Supplies
- Pets
- Sport & Outdoors
- Super Deals
- TikTok Growth & Monetization Mastery
- Travel
- Wealth
- Popular
- Best deals
Living Expenses Budget: How Much Should You Plan For?
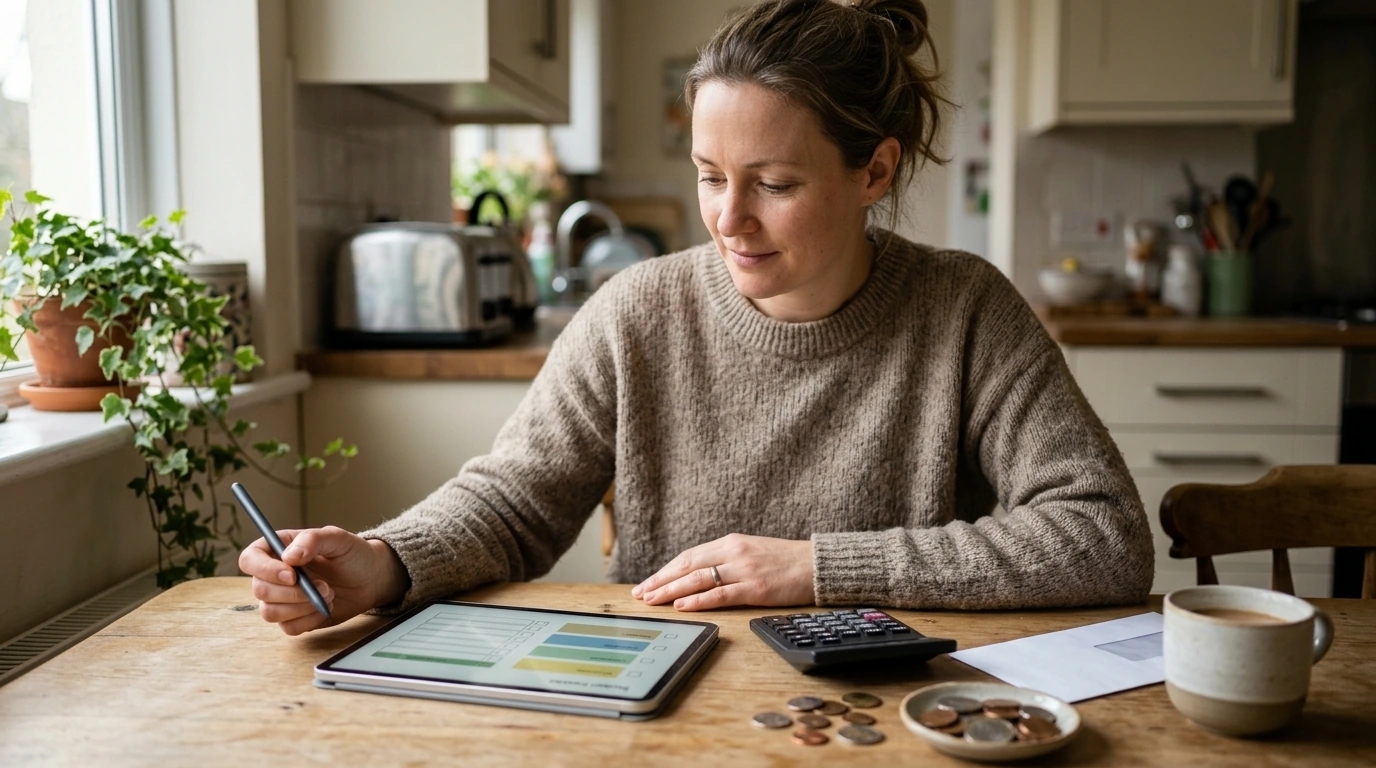
How much should you budget for living expenses?
Budgeting for living expenses starts with one practical goal: cover your essentials, keep your bills predictable, and leave room for real life. Our team recommends building your budget from your actual monthly numbers (not averages you’ve heard online), then adding a buffer so a surprise cost doesn’t derail you.
Start with your take-home pay
Use your net income (after taxes and deductions). If your income varies, base your plan on a conservative month, then treat extra income as a chance to catch up, save, or pay down debt.
List your “must-pay” basics first
For most households, the biggest living expenses are housing, utilities, groceries, transportation, insurance, and minimum debt payments. Add childcare, medical costs, and any required subscriptions (like phone/internet). These are your non-negotiables—the budget should protect them first.
Use a simple target split, then adjust
A common starting point is the 50/30/20 approach: about 50% for needs, 30% for wants, and 20% for savings and debt payoff beyond minimums. If your rent or mortgage is high, your “needs” category may be closer to 60%—that’s okay as long as you intentionally shrink other categories and build savings over time.
Add an “irregular expenses” cushion
Many budgets fail because they ignore non-monthly bills. Set aside money each month for car repairs, medical copays, gifts, annual fees, and home maintenance. Even $50–$200 monthly (or more, depending on your situation) can prevent a credit card spiral.
Make it livable with a weekly spending limit
After essentials, assign a weekly amount for flexible spending like dining out, fun, and small household purchases. This makes daily decisions easier and keeps you from overspending early in the month.
For a step-by-step checklist and category breakdown, use our guide: living expenses budget checklist.
FAQ
What’s the difference between fixed and variable expenses?
Fixed expenses stay about the same each month, like rent, insurance premiums, and loan payments. Variable expenses change month to month, like groceries, gas, and utilities, so they need tracking and a spending cap.
Recommended for you


Stream & Earn: 30-Day Plan to Grow Live Streams
Oct 15, 2026



Leave a comment