-
Shop
- Advanced Technologies
- Best-Sellers
- Car Accessories
- Dating & Social Skills
- Digital Resources
- Budgeting & Saving
- Emotional Intelligence
- Entrepreneurship & Business Growth
- Financial Independence
- Financial Mindset & Psychology
- Goal Setting
- Leadership
- Mindfulness
- Motivation
- Online Business
- Positive Thinking
- Productivity
- Self Confidence
- Sleep Improvement
- Stress Management & Relaxation
- Yoga & Mind-Body Practices
- Education & Learning
- Family & Parenting
- Fashion
- Alexander McQueen
- Bags
- Bags & Wallets
- Balenciaga
- Belts
- Blazers
- Blouses & Shirts
- Bottega Veneta
- Bottoms
- Brunello Cucinelli
- Burberry
- Chanel
- Chloé
- Dior
- Dolce & Gabbana
- Dresses
- Etro
- Fendi
- Gucci
- Jacquemus
- Jewelry
- Jil Sander
- Keychains
- Kiton
- Luggage
- Luggage Bags
- Miu Miu
- Off-White
- Outerwear
- Prada
- Rick Owens
- Saint Laurent
- Shoes
- Socks & Tights
- The Row
- Tom Ford
- Valentino
- Valentino Garavani
- Versace
- Vivienne Westwood
- Fashion Accessories
- Furniture
- Gadgets
- Guess
- Headphones
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Supplies
- Kids & Babies
- Kitchen
- Kitchen Best-Sellers
- Lighting
- Patio, Lawn & Garden
- Personal Growth
- Pet Care
- Pet Supplies
- Pets
- Sport & Outdoors
- Super Deals
- TikTok Growth & Monetization Mastery
- Travel
- Wealth
- Popular
- Best deals
Good Budget for Living Expenses: Percentages & Targets
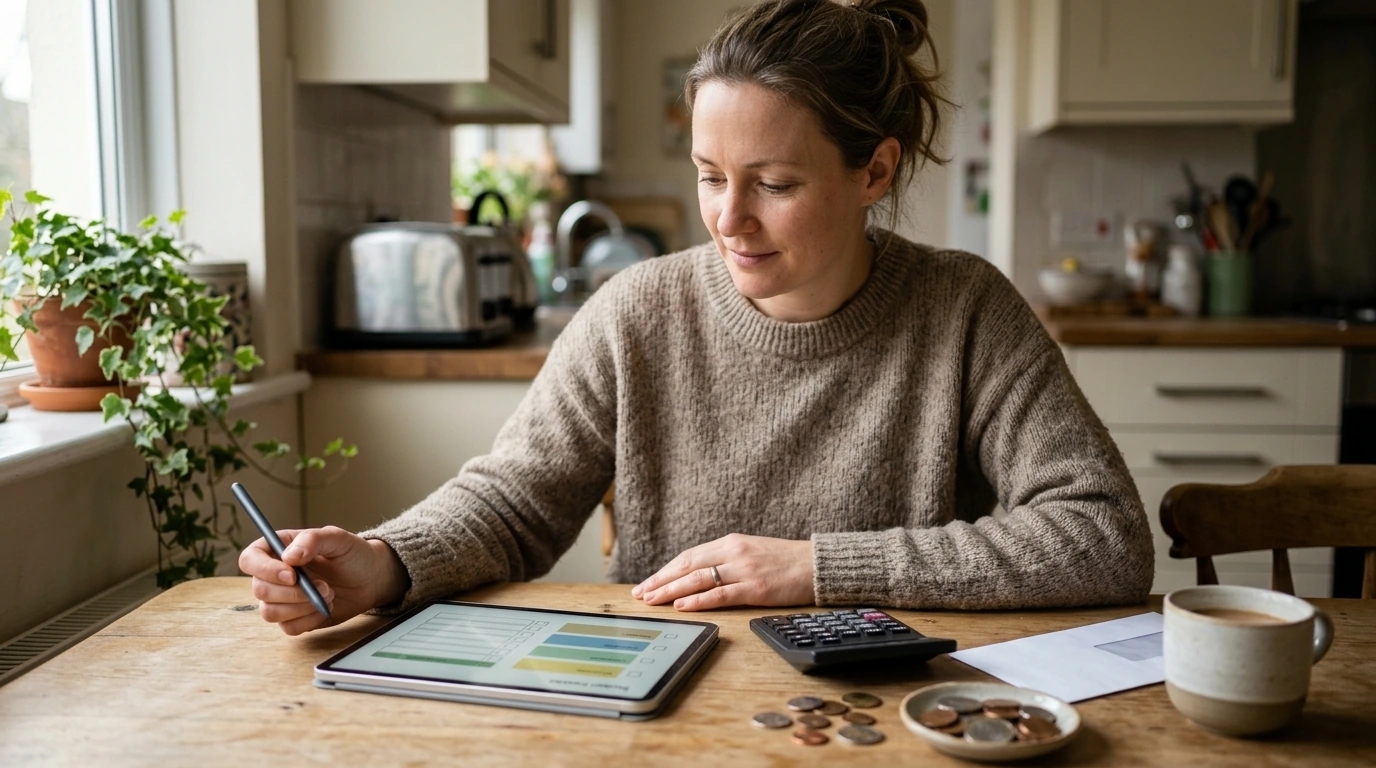
What is a good budget for living expenses?
A good budget for living expenses is one you can reliably cover every month without skipping essentials, while still leaving room for savings and a little breathing space. For many households, a practical starting point is keeping “needs” around 50% of take-home pay, “wants” around 30%, and savings/debt payoff around 20%. That said, high-rent areas, childcare costs, medical needs, or variable income can shift those ratios—so your best budget is based on your real numbers, not a one-size rule.
Start with your non-negotiables
Our team suggests you begin by totaling your fixed essentials: housing (rent/mortgage), utilities, basic groceries, transportation, insurance, minimum debt payments, and necessary healthcare. If these essentials are already above 60–70% of your take-home pay, your “good” budget should focus on stabilizing basics first—then gradually rebuilding savings once the foundation is secure.
Plan for the expenses that don’t show up every month
Living expenses aren’t just monthly bills. Add a line for “irregular essentials,” like car repairs, annual fees, gifts, school costs, and seasonal utility spikes. A simple approach is to total last year’s irregular spending and divide by 12 so you can set aside a consistent amount each month.
Use targets that reduce stress, not create it
A budget works when it’s realistic. If you’re new to budgeting, set a “baseline” target that covers essentials plus a small cushion, then add goals in layers: emergency fund, sinking funds (car/medical), and extra debt payments. For a step-by-step checklist and category breakdown, see our guide here: living expenses budget checklist.
FAQ
How much should I budget for living expenses?
A solid starting point is to budget 50–60% of your take-home pay for essentials like housing, utilities, groceries, transportation, insurance, and minimum debt payments. If housing or childcare is high, it may be closer to 70%, and then you’ll want to tighten “wants” and prioritize a small emergency buffer.





Leave a comment